Losing Your Business: What to Do Next, Step by Step
If you are losing your business, the most useful thing you can do today is stop reacting and start diagnosing. Look at your cash, your bills and your sales honestly, decide whether a short, bounded recovery plan can work, and get qualified legal and accounting advice if you may not be able to meet your obligations. Then look after yourself, because this kind of loss is as personal as it is financial.
This guide walks through the warning signs, the most common causes, a stabilization sequence, the save-or-close decision, the practical steps of closing, and how to recover and build again. It is written for freelancers, small business owners and early-stage founders, including those who work remotely or on the road.
TL;DR
- Cash-flow trouble, late bills, falling margins and lost key customers are the signals that matter most. Low profit despite high sales is a warning sign in its own right.
- Start by reviewing cash, bills and receivables, pausing nonessential spending, and talking early to vendors and lenders if timing is tight.
- Decide with a bounded plan: one owner, one deadline, a measurable result and a spending ceiling. If the plan fails the test, closing in an orderly way is a legitimate decision.
- If insolvency is possible, get legal and accounting advice right away. Rules differ by country and business structure.
- Name the loss, lean on people, keep a routine, and separate the business outcome from your self-worth. Your next venture can use everything you learned.
Table of Contents
- Is your business really failing? The warning signs
- Why businesses lose money in the first place
- Stabilize first: a practical sequence
- Save it or close it: a test you can run
- If you decide to close, do it in an orderly way
- The part nobody puts in the spreadsheet: grief
- Our perspective: a setback is data, and community is the multiplier
- Using the experience to plan what comes next
- Where Nomad Excel can help
- FAQ
- Sources
Is your business really failing? The warning signs
Feeling overwhelmed and being in serious trouble are not the same thing. The difference usually shows up in the numbers, and several official and professional bodies describe the same pattern.
Cash and bills. Government guidance from the UK lists cash-flow problems, late bills, late payroll tax payments, above-average interest on loans, and low profits despite high sales as signs of company distress. The same body’s company health check adds suppliers chasing late payments, trade accounts placed on stop, demands for payment in advance, and liabilities that exceed assets.
Profitability. Australia’s business.gov.au says being unable to pay yourself a salary, rising costs without rising profits, reliance on borrowing to operate, and difficulty getting finance all point to poor profitability.
Customers. The same guidance flags falling sales, the loss of major customers, and more complaints or refund requests as damaging changes in customer behavior.
Margins and stability. The ICAEW, a professional body for accountants, names six signs of distress: a persistent cash shortage, high interest payments, increasing bill defaults, stretched debtor or creditor days, falling margins, and unhappiness or instability among management. It also stresses that long-term survival depends on profit, not sales.
Formal pressure. A U.S. law firm’s distress guide lists creditor demands, court proceedings, suppliers putting the business on stop, lost key customers or suppliers, unavailable borrowing, covenant breaches and falling revenue among the serious indicators.
A quick self-check: if you can say yes to three or more of the following, treat it as serious.
- You regularly cannot pay a bill on time.
- Revenue is flat or rising, but cash left at month end keeps shrinking.
- You are borrowing to cover ordinary running costs.
- You have not paid yourself in months.
- Your biggest client or supplier has left or is about to.
- You dread opening the bank account or the inbox.
If it is only one or two, you may be facing a rough patch rather than a collapse, and the stabilization steps below can still help.
Why businesses lose money in the first place
Knowing the cause matters because the fix for a demand problem is nothing like the fix for a cash-timing problem. The U.S. Chamber of Commerce’s small business resource lists cash-flow problems, insufficient demand, poor management, financial challenges, poor employee management, inadequate marketing, failure to adapt to market changes and inventory mismanagement as common causes. CNBC, reporting on the Global Entrepreneurship Monitor’s 2013 U.S. data, noted that financing problems and lack of profitability led the reasons for discontinuing a business.
It helps to sort your own situation into one of four buckets:
| Problem type | What it looks like | First question to ask |
|---|---|---|
| Demand | Few leads, weak conversion, customers drifting away | Do enough people want this offer at this price? |
| Margin | Sales exist but profit does not | Which products, clients or tasks lose money? |
| Cash timing | Profitable on paper, short on cash | Who owes me, and when do I owe others? |
| Management | Missed deadlines, unclear roles, owner burnout | What am I doing that someone or something else could do? |
Most struggling businesses have more than one, but one is usually the lead problem. Find it first.
Stabilize first: a practical sequence
No single formula saves every business, but the order of operations is fairly consistent across the guidance owners rely on. Think of it as stopping the bleeding before you plan the surgery.
Step 1: See the real numbers
Pull together your bank balances, upcoming bills, outstanding invoices and debts in one place. The U.S. Small Business Administration emphasizes keeping up your bookkeeping and understanding your finances before you make any decision to sell, transfer or close. If your books are behind, catching them up is the first job, not the last.
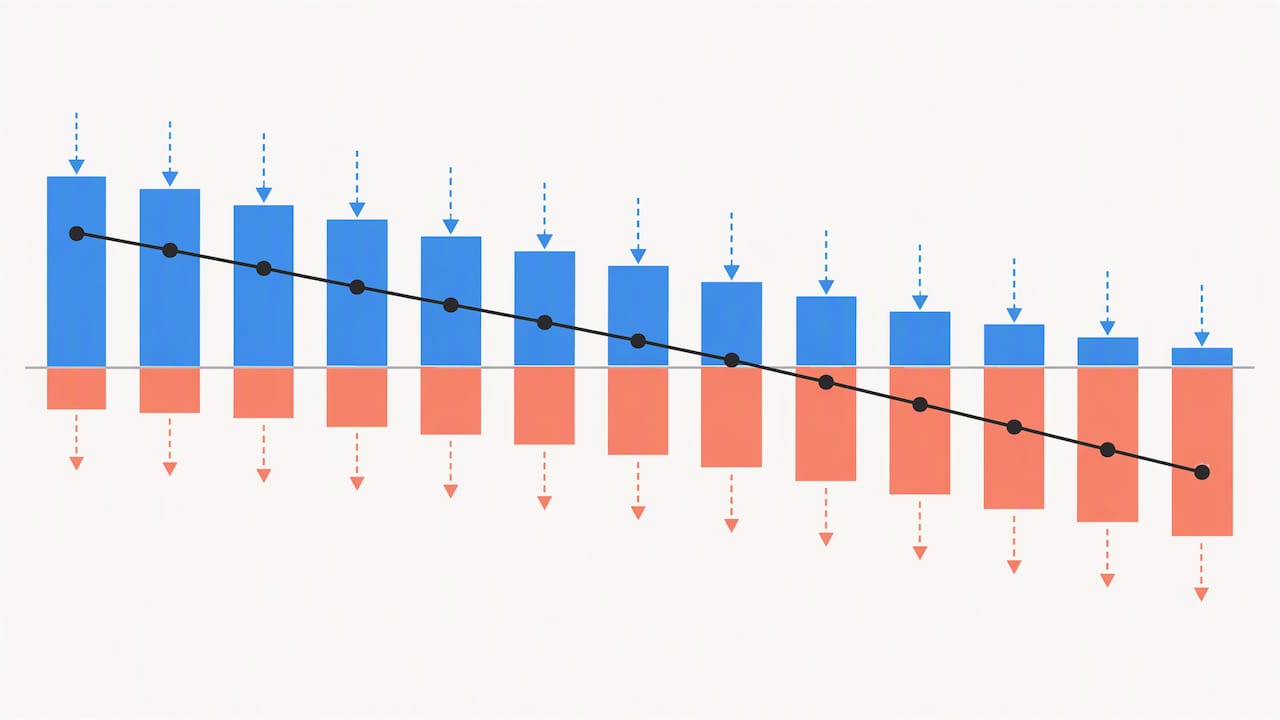
Build a simple 13-week cash view: expected money in, money out, and the week your balance could go negative. It does not need to be elegant. It needs to be honest.
Step 2: Pause nonessential spending
Cancel subscriptions you do not use, defer purchases, and separate costs that earn revenue from costs that merely feel professional. Do not cut the one thing that brings in clients unless the numbers say it does not work.
Step 3: Talk early to people you owe
Vendors and lenders tend to respond better to a call before a payment is missed than to silence afterward. Be specific: what you can pay, when, and what your plan is. Government guidance on company health lists suppliers’ demands and threats of recovery action as warning signs, which is exactly the situation early conversations can help you avoid.
Step 4: Examine sales and margins
List your offers, clients or products by revenue and by profit. Many owners find that a small share of their work produces most of their profit, and that some work loses money once time is counted. Raise prices where you can, stop low-value work, and speed up collections on overdue invoices.
Step 5: Get a second set of eyes
An accountant, a lawyer and a business adviser each see different things. In the U.S., one SBA case study describes a company near bankruptcy that worked with Small Business Development Center advisers to build a sustainable financial model and operating processes. Another describes owners who worked with an accountant and attorney, consolidated debt and refinanced assets to keep their company going. Outside advice is not an admission of failure. It is how many turnarounds start.
Step 6: Reduce your own workload with systems
If you are a solopreneur, part of the problem may be that you are the only engine. Once the urgent cash picture is stable, look at ways to automate parts of your business, such as invoicing reminders, onboarding and repeat reporting, so your limited hours go to selling and delivery.
Step 7: Measure weekly
Pick three numbers, such as sales, cash and one operating measure like delivery time or leads, and review them every week. Weekly numbers show whether a change is working in days, not quarters.
Save it or close it: a test you can run
The hardest question is not how to work harder. It is whether more effort will change the outcome. A bounded plan makes the answer less emotional.
Write down:
- The change you believe will improve the business, such as a new offer, a price rise or a lower cost base.
- An owner for it, which may be you.
- A deadline, often 60 to 90 days.
- A measurable result, such as monthly revenue or margin.
- A spending ceiling, the most cash you will put in before stopping.
- The downside scenario, meaning what you owe and own if it fails.
Then compare that plan with closure on facts: cash on hand, expected receipts and how confident you are in them, payroll and tax obligations, debts, customer commitments, leases and sellable assets. The Oregon Small Business Development Center’s closure guide advises reviewing past circumstances, assessing the present objectively, estimating future outcomes and getting legal and financial advice before you close.
A word on duties: if the business may be insolvent, the rules can change. In the UK, for example, government guidance states that when insolvency is possible, directors must put creditors’ interests ahead of their own and shareholders’. Other countries and U.S. states have their own rules, and they depend on whether you operate as a sole proprietor, LLC or corporation. If you cannot pay what you owe, speak to a licensed business attorney and an accountant in your jurisdiction before you take any further credit, move money or pay one creditor ahead of others.
If you decide to close, do it in an orderly way
Closing is a process, not a single moment. The SBA’s guidance on closing or selling treats it that way, covering professional advice, formal filings, employee compliance, tax resolution and record retention. A realistic checklist looks like this:
- Document the decision and the date.
- Get legal and accounting advice on your structure.
- Review ownership agreements, leases and contracts for exit terms.
- Plan how debts and taxes will be settled.
- Notify and pay employees as the law requires.
- Cancel registrations, licenses and online accounts.
- File dissolution or insolvency paperwork where required.
- Dispose of assets lawfully.
- Keep your records for the period your location requires.
Which of these apply, and in what order, depends on your structure and place. In the UK, for instance, a solvent company can apply for strike-off or start a members’ voluntary liquidation, while an insolvent one can enter administration, apply for strike-off or arrange a creditors’ voluntary liquidation. Liquidation there ends the company’s ability to trade and employ people and removes it from the register. U.S. readers should look at their state’s secretary of state page and the IRS rules for their entity type, with a professional’s help.
If you are a freelancer or sole proprietor without a formal entity, the steps are lighter but still real: finish client commitments or hand them off, settle outstanding invoices and taxes, close business accounts and keep your records.
The part nobody puts in the spreadsheet: grief
Losing a business is not only a financial event. It is tied up with identity, purpose, long hours and the people who believed in you. Business Queensland’s official closure guidance acknowledges that closing can be confronting for the owner, family and employees, and recommends building support from family, friends, a business adviser and mental-health services.
A Canadian tip sheet on entrepreneurial loss describes common reactions: shame, sadness, fear, anger, exhaustion, uncertainty and feeling lost. Its suggestions are practical and small:
- Name what you have lost, including income, status, routine and colleagues.
- Let the emotions come without judging them.
- Be patient with yourself.
- Ask for support, and accept it when it arrives.
- Eat regularly, rest, and exercise as your body needs.
- Keep a routine and write things down.
- Avoid things that only numb you.
If you notice persistent hopelessness, sleeplessness, or thoughts of harming yourself, contact a doctor or a mental-health professional. In the U.S. you can call or text 988, the Suicide & Crisis Lifeline, at any hour.
Our perspective: a setback is data, and community is the multiplier
We meet many people who are one decision away from either giving up or restarting more wisely. What we see again and again is that clarity beats intensity. Working harder on the wrong offer rarely helps, while a clear test, a clear owner and a clear deadline often does.
We also believe isolation makes everything heavier. Running a business alone, especially as a freelancer or remote founder, means no one challenges your assumptions and no one notices when you are slipping. That is why our programs combine hands-on workshops, mentorship from experienced entrepreneurs and operators, and a peer community that continues after the event ends. Execution, with daily accountability and structured sprints, is what turns insight into a result.
If you are closing a business, that is not the end of your entrepreneurial story. It may be the most valuable tuition you will ever pay, provided you take the lessons with you and do not carry the shame.
— Amichai
Using the experience to plan what comes next
Research on people who have been through this is encouraging. A peer-reviewed study of 277 Korean entrepreneurs with real failure experience found that coping strategies influence whether people intend to start again. Its practical advice includes separating the business failure from your self-worth, and using social-support networks and communities to share the emotional experience and apply the lessons. A Taiwanese case study found that personal motivation, the ability to learn from failure and family support helped an entrepreneur keep trying after repeated setbacks.
To turn that into a plan, write a short post-mortem within a few weeks, while the details are fresh:
- What did customers actually pay for? Not what you hoped.
- Where did the money go? Name the three biggest costs and whether each earned its place.
- Which assumption was wrong? Demand, price, channel, timing or capacity.
- What did you do well? Skills, relationships and processes you can reuse.
- What would you test first next time? Ideally something you can validate in days, with little cash.
If you want a lower-risk path back, consider a smaller first step: freelance work, a service offer, or a validation sprint before you commit savings. Our guide on how to make a small business grow covers proven growth strategies you can apply to whatever you build next, and our piece on why business education matters for entrepreneurs explains how structured learning shortens the trial-and-error phase.
Where Nomad Excel can help
If you are rebuilding, restarting or still trying to rescue your business, a structured, supportive environment can save months of guessing. Our Online Entrepreneurship Bootcamp is a practical place to start. Our Online Business Bootcamp is €500 one-off, and our 5-Day Online AI Bootcamp is €300 one-off. If you prefer to work in person with a cohort, we also run in-person bootcamps, including Entrepreneurship Sprint Bootcamps in Lisbon at €1,350 and €1,500 depending on the venue. See the full program overview for what each one includes.
FAQ
How do I know if I should close my business or keep going?
Test a bounded recovery plan against closure. Give the plan one owner, a deadline, a measurable result and a spending ceiling, and compare it with what closing would cost and return. If the plan misses its targets or would require money you cannot afford to lose, closing in an orderly way is often the more responsible choice. Speak to an accountant and attorney before deciding if you may be insolvent.
What are the first signs a business is about to fail?
The most consistent signs are persistent cash shortages, late bills, rising borrowing, falling margins, lost major customers and suppliers demanding advance payment. Low profit despite high sales is an especially important signal. One sign alone is not a verdict, but several together deserve immediate attention.
What should I do first if I am losing my business?
Gather your real numbers: cash, bills, receivables and debts. Pause nonessential spending, call key vendors and lenders before you miss payments, and find out which products or clients earn profit. Then book time with an accountant or a Small Business Development Center adviser.
How do I cope emotionally with losing a business?
Name what you have lost, accept the emotions that come, keep a routine, rest and eat regularly, and ask others for support. Try to separate the outcome of the business from your worth as a person. If low mood, hopelessness or sleeplessness persist, see a doctor or mental-health professional.
Can I start another business after one fails?
Yes, and many people do. Research on failed entrepreneurs links healthy coping and social support with the intention to try again. Do a clear post-mortem, validate small before you invest big, and surround yourself with peers who will challenge your assumptions.
Sources
- Director information hub: Signs of company distress, GOV.UK
- Company health check: keeping your business on track, GOV.UK
- Warning signs your business is in financial trouble, business.gov.au
- Six signs that a business is in distress, ICAEW
- Common Signs of Business Stress and Distress, Squire Patton Boggs
- Top Reasons Small Businesses Fail, U.S. Chamber of Commerce
- 11 all-too-common reasons small businesses fail, CNBC
- Close or sell your business, U.S. Small Business Administration
- Clackamas Calibration Company, SBA
- How Millennium Press Overcame a Crisis and Near Closure, SBA
- Business Closure guide, Oregon SBDC
- Closing a limited company, GOV.UK
- Guide to liquidation (winding up), GOV.UK
- Closing a business, Business Queensland
- Navigating Entrepreneurial Loss and Grief, Alberta Critical Incident Services
- How Do Failed Entrepreneurs Cope with Their Prior Failure, PMC
- Entrepreneurial business start-ups and entrepreneurial learning, PMC
Comments are closed.